For millions of households across the developing world, cross-border remittances represent far more than simple financial transactions; they constitute a vital economic lifeline. According to comprehensive data published by the World Bank, global remittance inflows into low- and middle-income countries surpassed an unprecedented $669 billion in 2023. In many emerging market economies, these financial transfers now account for a substantial percentage of gross domestic product (GDP), frequently eclipsing foreign direct investment (FDI) to become the single largest source of external foreign exchange.
Despite an influx of modern technology-driven challengers over the past decade, traditional financial institutions and legacy money transfer agents continue to maintain a formidable grip on the global market, retaining over 60 percent of the total market share. Nevertheless, a new wave of nimble, consumer-centric fintech platforms is aggressively chipping away at that dominance. While some early pioneers in the digital remittance space—such as Remitly—have successfully transitioned to public markets via initial public offerings, others like Zepz and Taptap Send remain privately held, fiercely competing for the remaining market share.
Entering this high-stakes landscape is LemFi, a London-headquartered financial services platform specifically engineered to meet the complex financial needs of global immigrant communities. The four-year-old fintech enterprise has officially announced the closure of a $53 million Series B funding round. Led by London-based growth-stage investment firm Highland Europe—which traditionally backs companies demonstrating annualized revenues exceeding €10 million—the round also saw enthusiastic participation from returning investors Left Lane Capital, Palm Drive Capital, and prominent startup accelerator Y Combinator. They were joined by new strategic participants, including Endeavor Catalyst, bringing LemFi’s cumulative venture capital funding to an impressive $85 million.
The Genesis and Rapid Ascent of LemFi
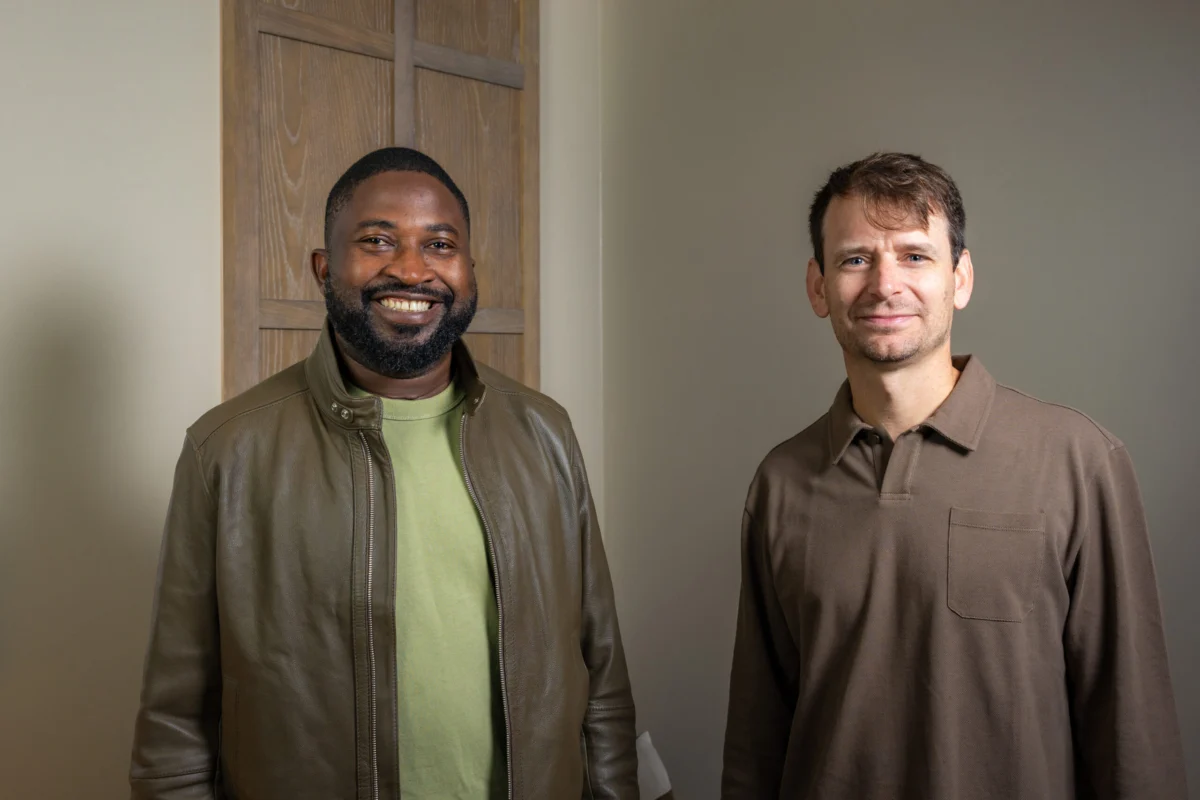
The foundational roots of LemFi trace back to 2020, when co-founders Ridwan Olalere and Rian Cochran established the enterprise. The two financial technology veterans crossed paths while working at OPay, the prominent African fintech unicorn backed by the SoftBank Vision Fund 2. Recognizing the profound friction, high fees, and opaque exchange rates that immigrant communities frequently encountered when moving money across international borders, Olalere and Cochran set out to build a streamlined, multi-currency account ecosystem tailored to the unique profiles of the global diaspora.
Since its commercial inception four years ago, LemFi has achieved explosive growth. The platform currently boasts a robust user base of over 1 million active customers. These users leverage LemFi’s digital multi-currency accounts to seamlessly transfer funds to friends, family members, and business associates across major emerging economic corridors, including Nigeria, Kenya, India, China, Pakistan, and 15 other developing nations.
Rather than relying on legacy correspondent banking networks that introduce unnecessary delays and layer on hidden charges, LemFi has engineered an adaptable, modular technology stack capable of rapidly plugging into disparate local payment schemes and regulatory frameworks. This technological agility has allowed the company to scale its geographic footprint efficiently. Following a recent European expansion strategy, LemFi now actively operates across 27 origin (send-from) markets and 20 destination (send-to) countries.
A Chronology of Strategic Expansion
LemFi’s trajectory from a fledgling startup to a billion-dollar monthly processing powerhouse is marked by calculated milestones and rapid operational execution:
- 2020: LemFi is officially founded in London by Ridwan Olalere and Rian Cochran, following their tenure at African fintech unicorn OPay.
- 2021–2022: The platform builds initial traction by serving diaspora communities in North America, facilitating seamless cross-border transfers to key African markets.
- April 2023: LemFi crosses a major operational milestone, recording over $2 billion in total annual transaction volume for the year, fueled by expanding product offerings and rising consumer adoption.
- April 2024: The company formally announces its strategic expansion into Asia, unlocking new high-volume corridors to cater to immigrant communities originating from nations such as India, China, and Pakistan.
- Late 2024: LemFi secures an initial operational foothold in Europe through a strategic partnership with embedded finance provider Modulr, bridging the gap ahead of regulatory licensing.
- Present Day: The company closes a $53 million Series B funding round led by Highland Europe, bringing its total institutional funding to $85 million and cementing its position as a major player in the global remittance ecosystem.
Conquering the European Market
LemFi’s most recent geographic push centers heavily on the lucrative European market. Last week, the fintech announced a strategic partnership with embedded finance provider Modulr. This calculated alliance enables LemFi to initiate local operations immediately across European jurisdictions while it awaits the final regulatory clearance slated for next month, following its acquisition of a Republic of Ireland-based financial firm.
By establishing a compliant and scalable operational base within the European Union and the United Kingdom, LemFi aims to capture a significant share of the remittance flows generated by Europe’s vast migrant populations. The company’s primary revenue streams are derived transparently from transaction fees and foreign exchange (FX) spreads, positioning it as a cost-effective alternative to traditional wire services and legacy high-street banks.
Despite the inherent regulatory complexities of navigating multiple sovereign jurisdictions simultaneously, LemFi’s leadership remains confident in the company’s structural readiness. “While regulations market by market remain complex and we have more stakeholders to deal with, scaling has become a lot easier for us because we have technology that is adaptable and can easily plug and play to different payment methods and schemes,” CEO Ridwan Olalere noted in an interview. “So, we intend to go to as many markets as we have significant number of immigrants, starting now with Europe this year, which is going to be a big focus for us.”
Mitigating Fraud to Drive Consumer Retention
One of the foundational pillars of LemFi’s rapid market penetration has been its uncompromising approach to security and risk management. Within the global remittance sector, financial fraud remains an existential threat to both service providers and consumers. According to recent industry analytics from Electronic Payments International, individuals who regularly send money across international borders are nearly four times more likely to fall victim to financial fraud and scams compared to domestic-only financial consumers.
Fraudulent activities, chargebacks, and compliance failures inevitably inflate operational overhead for fintech platforms, costs that are typically passed down to everyday consumers in the form of steeper transaction fees and less favorable exchange rates. LemFi has systematically circumvented this industry pitfall by deploying advanced, proprietary fraud-detection algorithms and real-time transaction monitoring systems.
“Fraud can significantly drive up costs. Higher costs often mean passing them on to customers through additional fees. We’ve managed to keep our fraud rate extremely low, allowing us to offer customers the best possible prices,” Olalere explained.
This strict adherence to security, paired with an intuitive, consumer-first user experience, has yielded exceptional customer loyalty metrics. According to company disclosures, approximately 70 percent of LemFi’s earliest foundational customers continue to utilize the platform actively, while an impressive 60 percent of the broader customer base remains active on an annual basis. Furthermore, this high level of user satisfaction has driven robust organic growth through word-of-mouth referrals, allowing LemFi to acquire customers efficiently without incurring unsustainable marketing expenditures.
Explosive Transaction Volumes and Financial Metrics
Investor confidence in LemFi’s business model is heavily anchored in its extraordinary financial momentum. When Olalere detailed the company’s strategic expansion into Asian markets in April 2024, the fintech reported an annualized transaction volume of $2 billion for the preceding year.
In the months since that announcement, those figures have experienced a dramatic acceleration. LemFi is now processing an astonishing $1 billion in monthly payment volume (TPV), effectively matching its entire annual volume from just a year prior within a 30-day window.
Olalere attributes this staggering growth primarily to the rapid adoption of the platform within the newly established Asian remittance corridors. Within its first year of launch, the Asian corridor alone has scaled to generate $160 million in monthly TPV, maintaining a blistering month-on-month growth rate of 30 percent. Over the past two years, the company has successfully doubled its aggregate user base, total revenue, and transaction counts—metrics that proved instrumental in attracting the attention of institutional growth-fund investors during the Series B negotiations, which Olalere noted were successfully finalized in just four months.
Strategic Deployment of New Capital
With $53 million in fresh capital now secured, LemFi’s executive team has laid out a clear blueprint for deployment. The newly acquired funds will be channeled into three core strategic pillars: product diversification, regulatory licensing, and talent acquisition.
- Product and Service Extension: LemFi plans to expand its suite of financial products beyond basic cross-border transfers, introducing enhanced multi-currency management tools, localized savings options, and expanded bill-payment capabilities tailored to diaspora families.
- Regulatory Scaling and Partnerships: The company will continue to secure direct payment network licenses and deepen its embedded finance partnerships worldwide, ensuring localized, compliant, and frictionless financial service delivery across diverse regulatory environments.
- Talent Acquisition and Organizational Growth: To support its next phase of global scaling, LemFi intends to actively recruit top-tier engineering, compliance, product, and operational talent. The firm currently employs a distributed workforce of over 300 professionals stationed across offices in Europe, North America, Africa, and Asia.
Broader Implications for the Global Fintech Landscape
LemFi’s rapid ascent underscores a broader structural transformation within the global financial architecture. As traditional banking institutions scale back their correspondent banking relationships—often driven by stringent anti-money laundering (AML) and know-your-customer (KYC) compliance burdens—millions of underbanked and unbanked individuals in emerging markets risk being financially marginalized.
Technology-forward platforms like LemFi are effectively filling this systemic void by leveraging modern software infrastructure to reduce transaction friction and democratize access to foreign exchange. By combining aggressive fraud prevention with hyper-localized user experiences, these fintech challengers are redefining consumer expectations in markets that have historically been underserved by legacy institutions.
As LemFi deploys its newly secured capital to deepen its footprint across Europe, North America, Africa, and Asia, the competitive dynamics of the $669 billion global remittance market are poised for continued disruption. For the millions of diaspora workers supporting families back home, the emergence of faster, safer, and more affordable financial conduits marks a profound shift toward greater economic inclusion on a global scale.