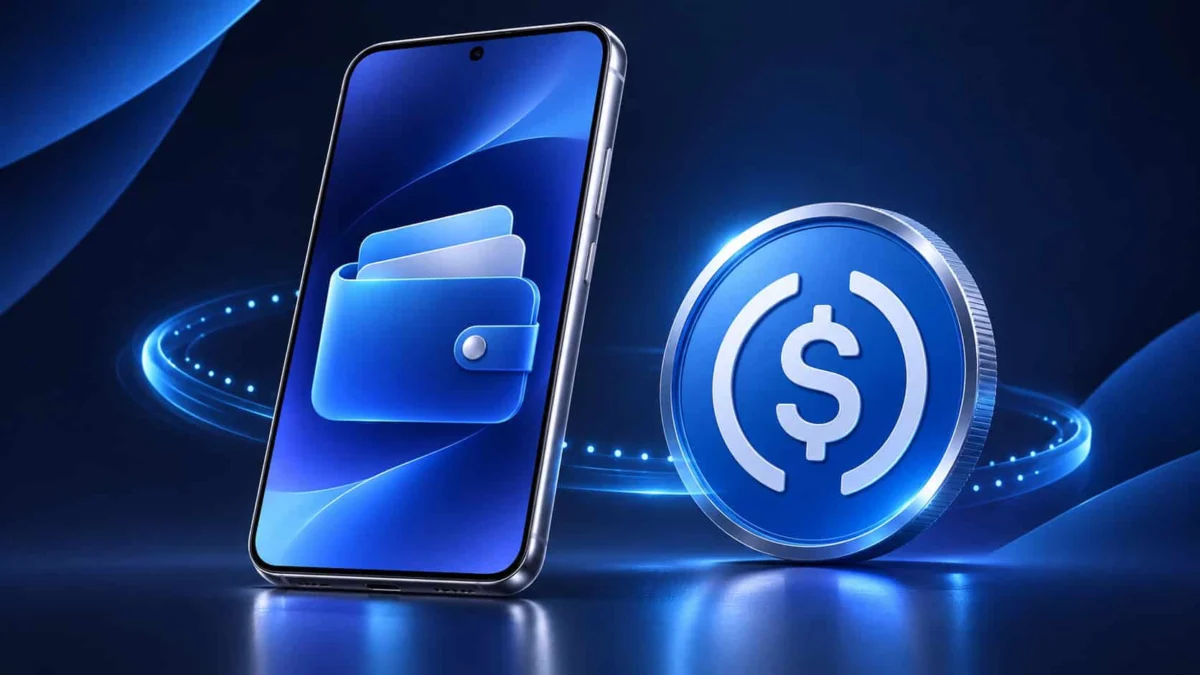
Samsung Electronics has significantly deepened its footprint in the digital asset ecosystem by officially launching USD Coin (USDC) purchasing capabilities within Samsung Wallet, anchored by payments giant Stripe. Unveiled through coordinated announcements from both technology leaders, the integration introduces a streamlined mechanism for eligible U.S. Galaxy device owners to acquire and manage the dollar-pegged stablecoin directly through a native mobile application. By embedding blockchain-based rails into a pre-installed consumer interface, the initiative aims to bridge the gap between traditional fiat payment methods and decentralized finance infrastructure, offering a frictionless entry point for millions of smartphone users who might otherwise hesitate to navigate complex cryptocurrency exchanges.
The strategic partnership relies on Stripe’s Crypto Onramp infrastructure to facilitate secure, compliant transactions within the newly established Samsung Wallet Stablecoin Account. According to official disclosures, the service boasts a potential reach spanning 82 million compatible Galaxy devices across the United States. This hardware footprint represents the total addressable market of eligible smartphones running Android 13 or later with functional fingerprint authentication, rather than an active tally of registered accounts or ongoing stablecoin users. While neither Stripe nor Samsung has disclosed initial transactional volumes or user sign-up counts, the sheer scale of the device distribution establishes one of the most prominent consumer-facing deployments of stablecoin technology to date.
An Evolving Chronology: From Concept to Consumer Rollout
The integration of Stripe’s payment architecture represents a critical operational milestone in a rollout strategy that began taking shape in late 202 previamente. The chronology of the deployment highlights a carefully orchestrated release schedule designed to align mobile software capabilities with institutional-grade backend security.
The initiative first gained public visibility on October 7, when Samsung Electronics formally announced plans to introduce stablecoin access to its U.S. customer base during the final week of October. Executives positioned the move as a major step forward in modernizing international remittances and consumer payments. Woncheol Chai, Executive Vice President and Head of the Digital Wallet Team at Samsung, emphasized the core consumer value proposition at the time, stating that sending money across borders should feel as convenient as using the wallet already built into a consumer’s phone.
Following the initial hardware and software scheduling, Stripe released complementary details on November 5, confirming that its Crypto Onramp infrastructure serves as the primary engine driving purchases within the Samsung Wallet Stablecoin Account. This technological backend manages complex compliance requirements, including identity verification checks and automated fraud prevention protocols. Furthermore, the collaboration establishes a reciprocal utility: Samsung Pay has simultaneously been integrated into Stripe’s broader Crypto Onramp network, allowing other commercial enterprises leveraging Stripe to accept Samsung Pay as a funding mechanism for digital asset purchases.
Underpinning the Technical and Financial Architecture
Behind the consumer-facing mobile interface lies a robust network of institutional partners and cryptographic infrastructure designed to ensure security, liquidity, and regulatory alignment. Samsung has enlisted specialized digital asset entities to manage custody and transfer execution. Bastion operates as a key infrastructure provider, while Coinbase serves as the sub-custodian, securing user-held USDC through the institutional-grade Coinbase Prime Vault framework.
For end users seeking to fund their accounts, the Stripe integration supports a wide variety of payment channels. Galaxy device owners can acquire USDC using traditional funding methods, including Samsung Pay, major credit and debit cards, and Automated Clearing House (ACH) bank transfers. Once funded, the Samsung Wallet Stablecoin Account permits users to hold, receive, and dispatch digital dollars, alongside participating in optional rewards programs.
Crucially, the system facilitates cross-border remittances to compatible crypto wallets and verified bank accounts in more than 60 countries. When funds are directed to foreign bank accounts, the receiving institution automatically converts the digital dollars into local fiat currency. Samsung has structured its fee schedule to be transparent: the company levies no internal fees for USDC transfers routed to supported external wallets, though external network conditions and recipient-side charges may apply. For bank remittances, costs and estimated delivery windows vary based on destination and transfer volume, with exact fees clearly displayed before the user confirms the transaction.
Regulatory Boundaries and Consumer Disclosures
While the integration emphasizes user-friendliness, Samsung and its partners maintain strict regulatory and jurisdictional boundaries. Participation in the Samsung Wallet Stablecoin Account is restricted to individuals aged 18 and older residing in eligible U.S. jurisdictions, with residents of New York state currently excluded from the service due to local regulatory frameworks.
Furthermore, consumer protection disclosures explicitly differentiate stablecoin balances from traditional banking products. Samsung’s official terms state clearly that the account holds digital assets rather than bank deposits. Consequently, balances, transfers, and accumulated rewards do not carry federal insurance protections from the Federal Deposit Insurance Corporation (FDIC), the National Credit Union Administration (NCUA), or the Securities Investor Protection Corporation (SIPC).
These structural distinctions underscore the importance of evaluating total transaction costs against legacy financial services. While the convenience of a native mobile wallet reduces friction, consumer adoption will ultimately depend on whether the total cost—factoring in funding fees, network conditions, and payout conversion rates—proves more economical than traditional international wire services or legacy remittance providers.
The Macroeconomic Landscape: USDC Reserves and Market Reach
The choice of USDC as the foundational stablecoin for Samsung’s wallet ecosystem places the feature within a multi-billion-dollar liquidity network. Issued by Circle Internet Financial, USDC is designed to maintain a strict one-to-one peg with the U.S. dollar, backed entirely by highly liquid cash and cash-equivalent reserves. As of early November, Circle reported approximately $69.2 billion in USDC circulating across various blockchain networks.
To maintain market confidence, Circle separates its reserve assets from operational corporate funds, publishing weekly transparency disclosures alongside detailed issuance and redemption metrics. Independent monthly assurance reports provided by major public accounting firms further verify the adequacy of reserve coverage. This structural transparency separates stablecoins like USDC from speculative cryptocurrencies such as Bitcoin, as the primary objective is maintaining dollar parity rather than capital appreciation through market volatility.
Industry analysts note that the ultimate success of stablecoins relies heavily on distribution infrastructure rather than protocol-level innovation alone. By embedding access directly into mainstream consumer hardware, initiatives like the Samsung Wallet integration provide a tangible case study in mainstream distribution strategy. Consumers utilizing the app to send funds abroad are less likely to focus on the underlying blockchain architecture and more concerned with delivery speed, exchange rates, and predictability.
Implications and the Road Ahead for Mobile Digital Assets
The integration of Stripe-powered USDC purchases within Samsung Wallet marks a significant evolutionary step for consumer fintech, merging the ubiquity of smartphone-based mobile wallets with the settlement speed of blockchain networks. By streamlining the onboarding process—allowing everyday users to fund stablecoin accounts using familiar payment cards or ACH transfers—the partnership removes traditional barriers that have historically kept digital assets confined to crypto-native platforms.
However, the long-term viability of the service will be measured by sustained consumer engagement rather than initial device reach. The primary test facing Samsung and Stripe is whether the convenience of purchasing and transferring digital dollars translates into routine, repeat usage. If users embrace the platform for everyday cross-border remittances and peer-to-peer transfers, the integration could serve as a powerful catalyst for mainstream stablecoin normalization. Conversely, if the feature remains an experimental novelty tried once and subsequently abandoned, it will highlight the ongoing challenge of altering deeply entrenched consumer payment habits. As the rollout progresses, industry observers will closely monitor activation rates, transaction volumes, and user retention to gauge whether mobile wallet stablecoin access can successfully scale to a mass-market audience.