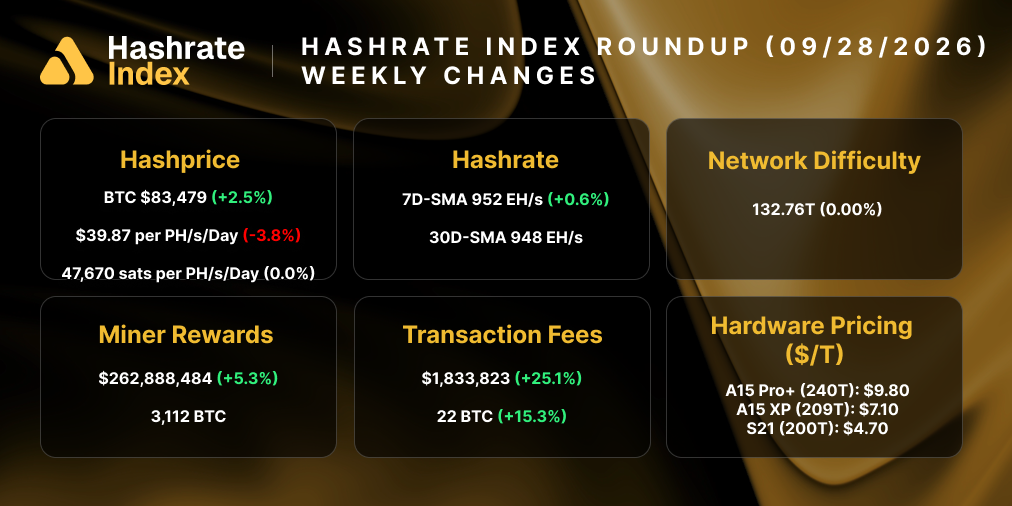
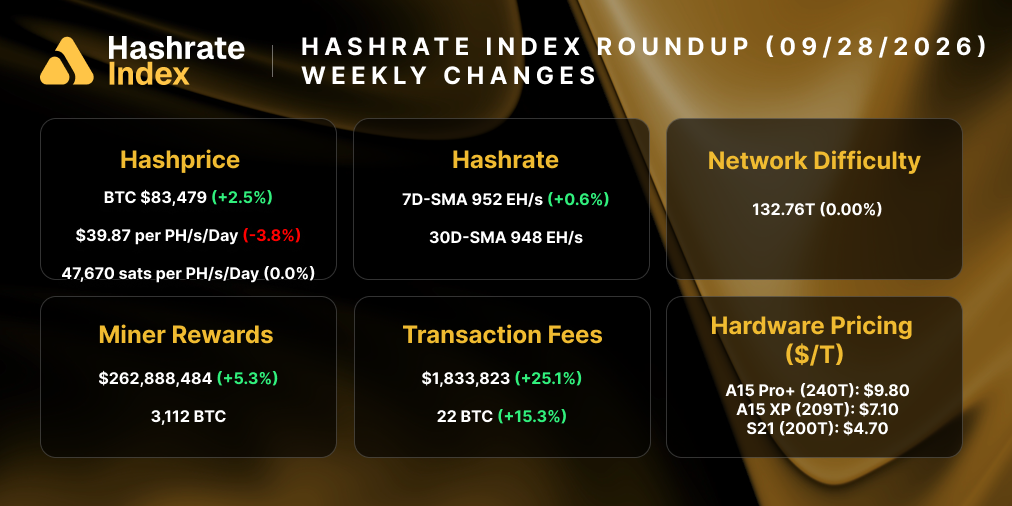
The Bitcoin mining sector concluded the final week of September 2026 with a complex performance landscape, characterized by rising asset prices and increased network hashrate, contrasted against a notable contraction in miner profitability. As of September 28, 2026, Bitcoin spot prices demonstrated resilience, appreciating by approximately 2.5% over the trailing seven-day period to settle near $83,479. Despite this positive price action in the underlying asset, the economic environment for mining operators remains challenging, as indicated by a decline in the USD-denominated hashprice—a critical metric representing the expected revenue for a specific unit of hashing power.
Market Dynamics and Revenue Metrics
Throughout the week ending September 28, the Bitcoin network processed a steady volume of transactions, allowing miners to collect approximately 3,112 BTC in total block rewards, representing an estimated value of $262 million. While the majority of this revenue is derived from the block subsidy, transaction fees contributed an additional 22 BTC, or roughly $1.83 million, to the miners’ coffers. Notably, transaction fees saw a 12% increase compared to the previous week, rising from an average of 0.0194 BTC to 0.0217 BTC per block.
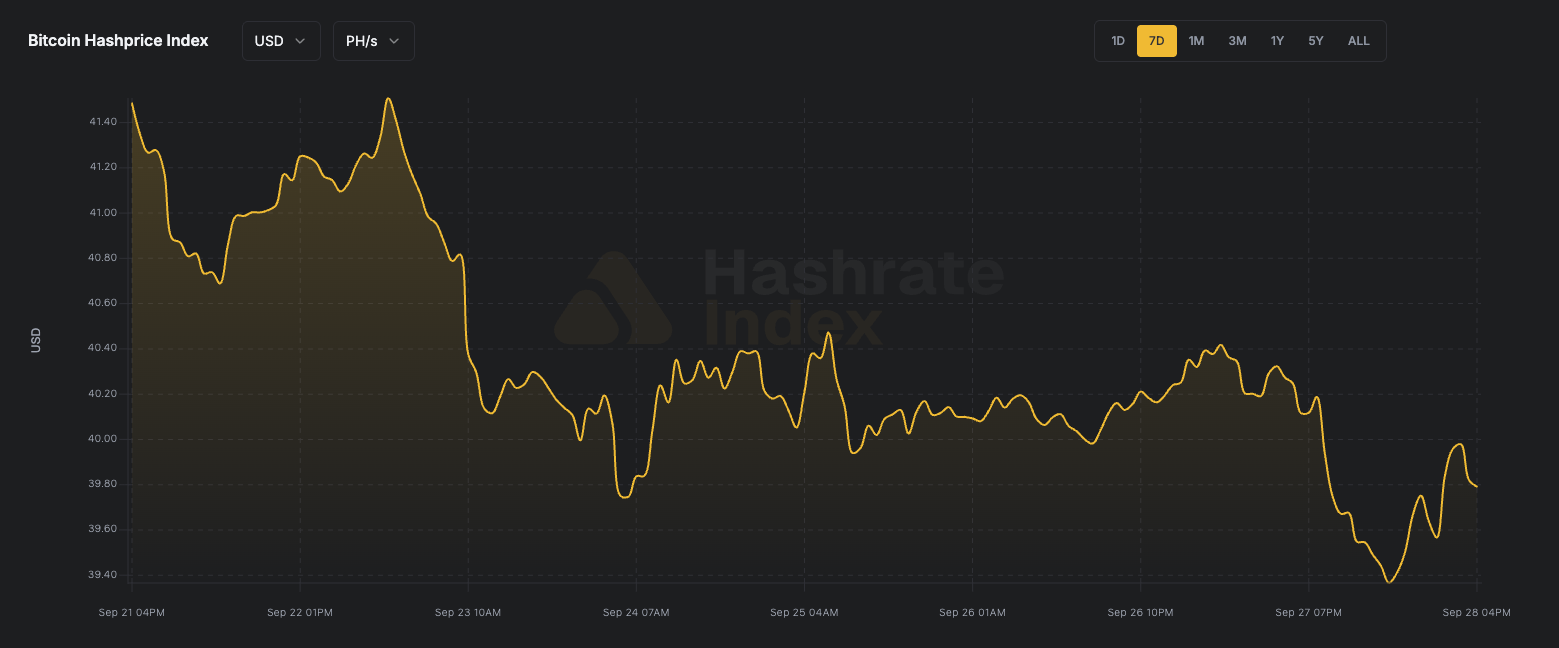
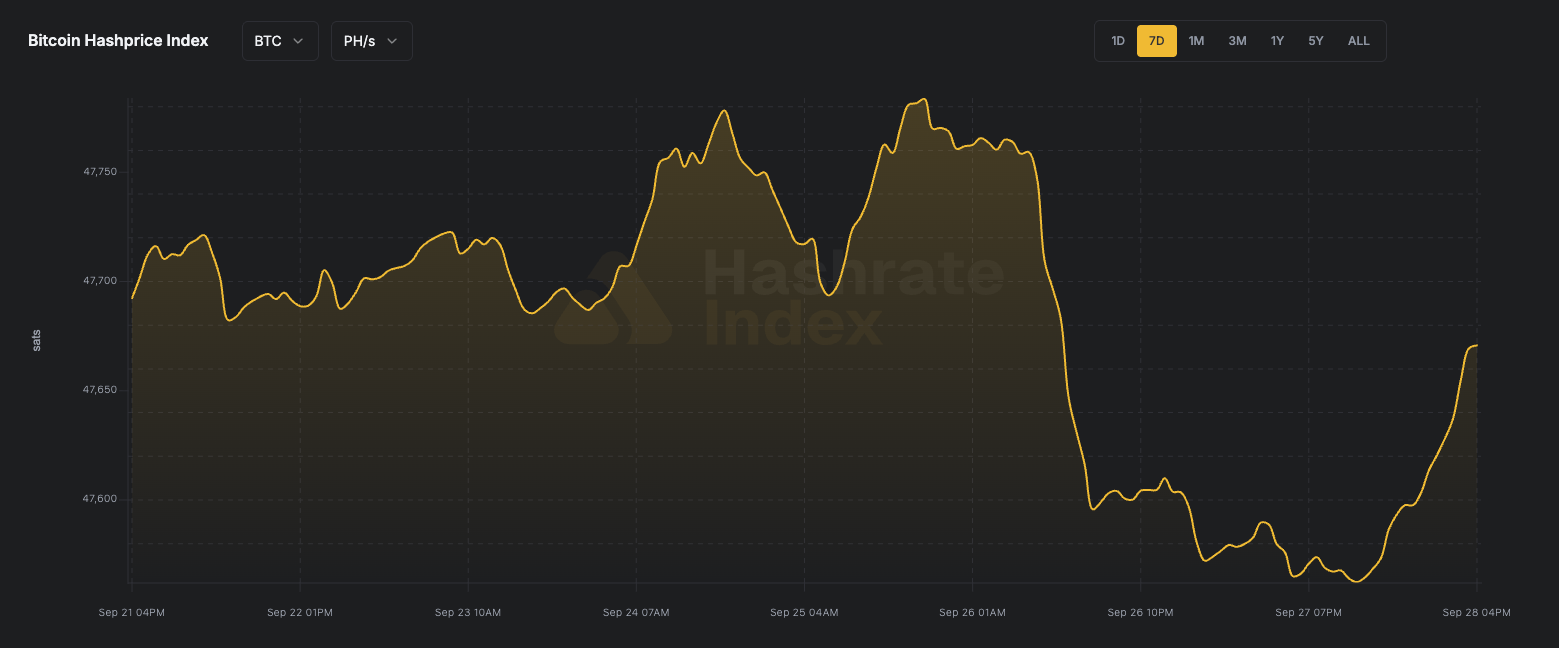
However, the uptick in Bitcoin’s spot price was insufficient to offset the impact of increased network competition on individual miner profitability. The USD hashprice dropped by 3.8% over the week, moving from $41.45 to $39.87 per PH/s/Day. This contraction highlights a persistent theme in the current mining cycle: as network difficulty remains elevated and the block subsidy remains fixed, the margins for operators are dictated heavily by their energy efficiency and the cost of electricity. For many, the current hashprice level of roughly $40 per PH/s/Day sits at or near the breakeven point, forcing a greater reliance on advanced firmware and optimized fleet management to remain competitive.
Network Hashrate and Difficulty Adjustments
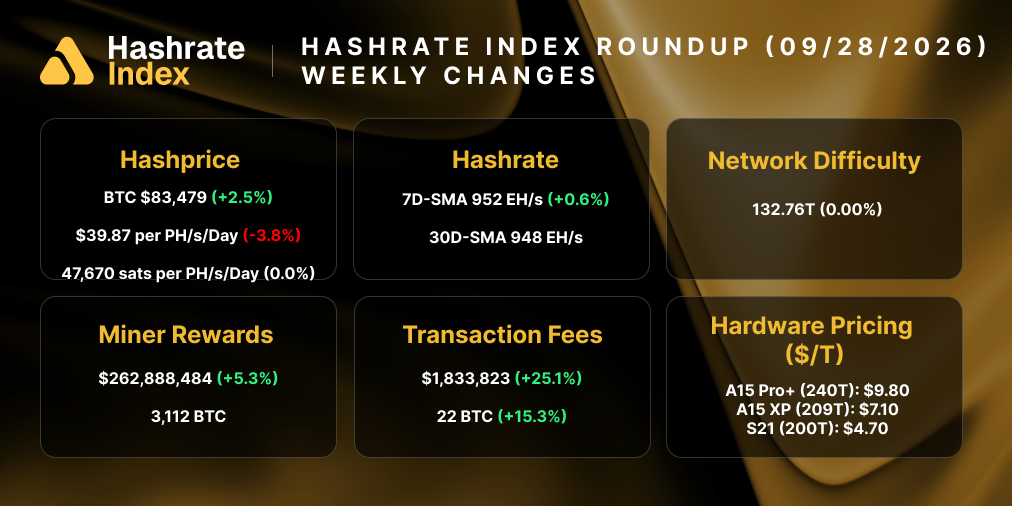
The Bitcoin network’s security, measured by its aggregate hashrate, continued its upward trajectory, reflecting the ongoing deployment of next-generation ASIC hardware. The 7-day simple moving average (SMA) of the network hashrate rose to 952 EH/s, up from 946 EH/s the previous week. This sustained growth in hashrate serves as a testament to the institutionalization of mining, where larger, well-capitalized operations continue to expand their infrastructure despite the tightening profit margins.
The most recent network difficulty adjustment, which occurred on September 19, 2026, saw an increase of 4.16%, bringing the network difficulty to 132.76T. This adjustment naturally squeezed the profitability of older, less efficient hardware, contributing to the downward pressure on the hashprice. Looking ahead, market analysts anticipate a slight reprieve in the next difficulty adjustment, currently projected for October 3, 2026, which is estimated to result in a minor decrease of 0.66%. Such fluctuations in difficulty are standard components of the Bitcoin protocol’s self-regulating mechanism, ensuring that block production times remain consistent at approximately 10 minutes, despite changes in total network computing power.
The Landscape of Mining Equities
The broader financial performance of publicly traded Bitcoin mining companies painted a somber picture during the week ending September 28. Mining stocks experienced a broad-based decline, with nearly every major player in the sector seeing a contraction in market capitalization. Investors appeared to be pricing in the potential for continued margin compression, as evidenced by significant drops in tickers like AIBZ, which fell by 17.6%, and DMGI, which saw a 16.7% decline.
Other industry stalwarts faced similar headwinds: Bitdeer (BTDR) fell 16.1%, Cipher Mining (CIFR) decreased by 11.4%, and Marathon Digital (MARA) saw an 8.8% reduction in its stock price. These declines suggest that the equity markets remain sensitive to the volatility of hashprice and the operational risks inherent in large-scale mining. The market cap of industry leaders like IREN, which holds a valuation of $16.44 billion, continues to be a focal point for institutional investors, yet even these giants were not immune to the sector-wide cooling that occurred over the last five days of trading.
Strategic Implications for Miners
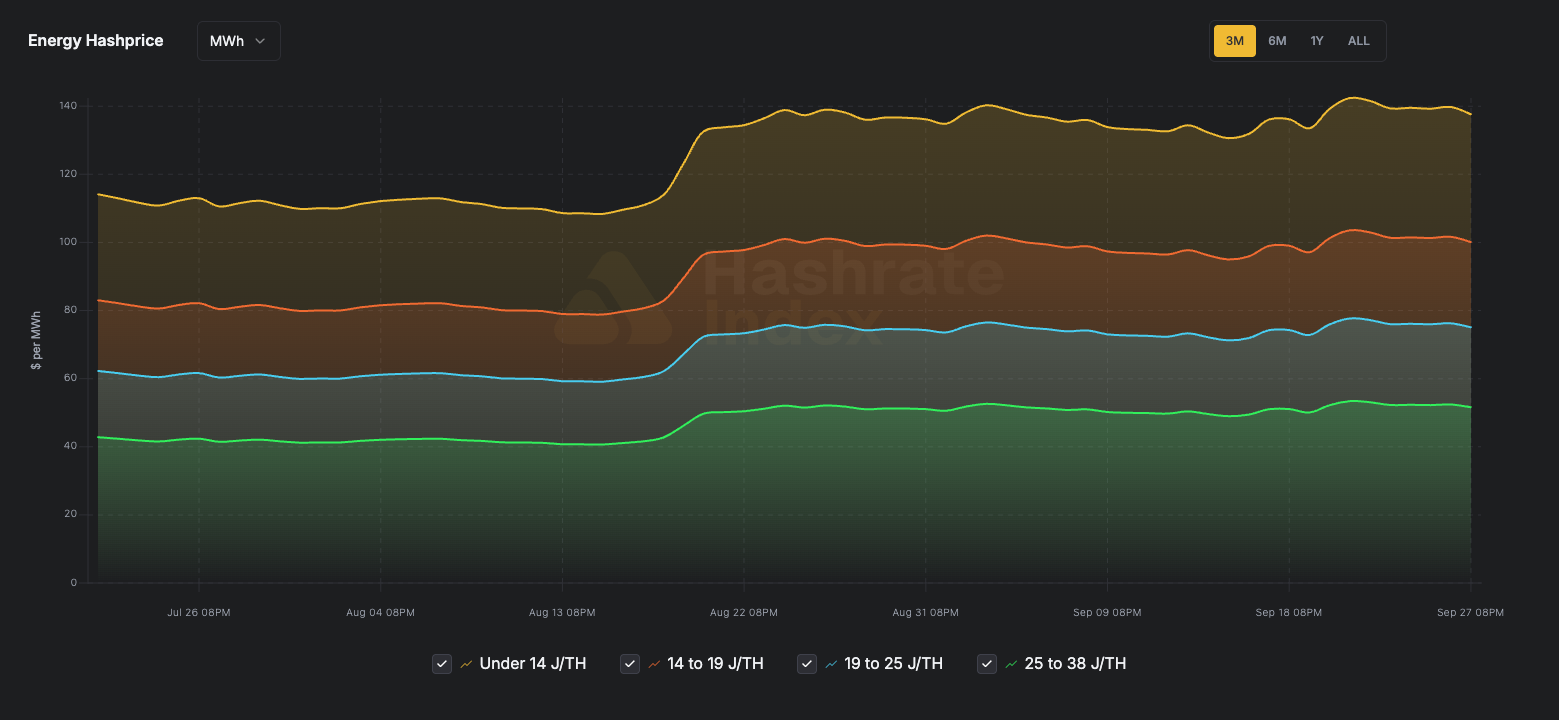
The current market environment necessitates a shift in strategy for many mining operations. With the hashprice hovering around the $40 threshold, firms are increasingly focusing on vertical integration and energy management. Many operators are turning to proprietary firmware solutions—such as those offered by Luxor Technology—to squeeze additional terahashes out of existing S19 and S21 series hardware. By improving the power-to-hashrate ratio, these firms hope to lower their effective cost per Bitcoin mined, thereby creating a buffer against future hashprice volatility.
Furthermore, the forward market for hashrate provides a window into industry expectations for the coming months. Data from the Luxor Hashrate Forward Market indicates that the industry is pricing in an average hashprice of approximately $38.34 over the next six months. This forward-looking data suggests that while miners may be hopeful for a price breakout in the underlying asset, they are bracing for a period of continued competitive pressure and potentially higher difficulty levels.
Broader Impact and Industry Outlook
The divergence between Bitcoin’s price appreciation and the decline in mining profitability underscores the "arms race" nature of the industry. As more efficient hardware is deployed, the network difficulty rises, effectively "baking in" the cost of security into the protocol. This cycle rewards those with access to the lowest-cost power and the most efficient hardware, while simultaneously forcing a consolidation of the mining landscape.
From a macroeconomic perspective, the health of the Bitcoin mining industry serves as a proxy for the broader confidence in the digital asset ecosystem. Despite the recent dip in equity values and the tightening margins, the fact that the hashrate continues to grow at such a rapid pace suggests that miners remain committed to the long-term viability of the network. The ability of these firms to weather periods of low hashprice will likely be a defining feature of the next year, as the industry matures and moves toward greater energy efficiency and financial sophistication.
As we look toward October, market participants will be closely monitoring the upcoming difficulty adjustment and its impact on block production times. Additionally, the continued volatility in mining equities will likely prompt a re-evaluation of valuation models for these companies, shifting the focus from pure revenue growth to operational efficiency and sustainable cost structures. The coming weeks will be critical for determining whether the current consolidation in mining stocks is a temporary correction or a broader re-rating of the sector’s long-term profitability potential.
For operators, the mantra remains unchanged: optimize for efficiency, manage energy costs, and maintain a focus on long-term capacity. As the network approaches 1,000 EH/s, the challenges of mining will only grow more pronounced, but so too will the resilience of the network they serve to secure. With the market currently navigating a complex interplay of price, difficulty, and hardware innovation, the mining sector continues to demonstrate its role as the backbone of the Bitcoin economy, consistently adapting to the rigorous demands of the proof-of-work protocol.