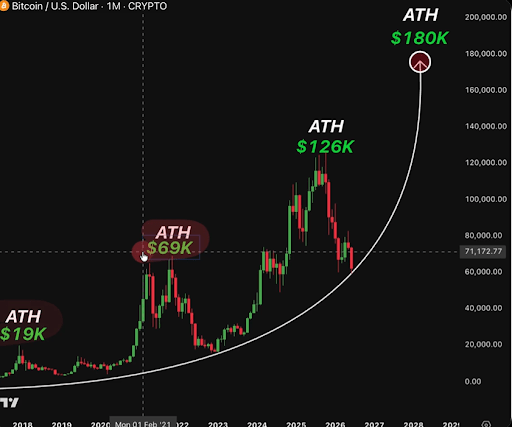
The global cryptocurrency landscape has long defied a single, monolithic definition, functioning simultaneously as a technological upgrade for institutional capital allocators in the West, an essential financial lifeline for low-wage workers navigating economic instability in the Global South, and a widely accessible alternative investment asset class for everyday retail participants worldwide. This multifaceted identity faced one of its most punishing trials in blockchain history between July 1, 2025, and June 30, 2026. During this twelve-month period, digital asset markets experienced a severe contraction characterized by Bitcoin climbing to a historic all-time high before suffering its largest-ever dollar-value retreat, shedding roughly $67,000 from peak to trough. This massive correction triggered a broader 50% drawdown in the aggregate crypto market capitalization, erasing an estimated $2.1 trillion in value and marking the most challenging bear market the industry has faced since the cascading corporate collapses and regulatory scandals of 2022.
Despite the profound depth of this valuation pullback, comprehensive data compiled in the latest annual Geographies report reveals that the global crypto economy—measured through a combination of service inflows, domestic peer-to-peer (P2P) transactions, and cross-border value transfers—contracted by a remarkably modest 1.6%. Total on-chain economic activity for the 12-month period ending June 30, 2026, held steady at approximately $9.4 trillion, declining only slightly from the $9.5 trillion recorded during the previous annual cycle. Financial analysts and industry experts point to this minimal contraction as empirical evidence that cryptocurrency usage has matured beyond pure speculation, anchored increasingly by real-world utility, cross-border commerce, and financial survival mechanisms in developing regions.

Chronology of the 2025–2026 Market Correction and Valuation Shock
To understand the resilience of the global crypto economy, market analysts must examine the volatile timeline that defined the 2025–2026 reporting period. The stretch began with robust bullish momentum that carried leading assets like Bitcoin into unprecedented price territory, inspiring widespread retail and institutional optimism. However, macroeconomic headwinds, tightening global liquidity, and shifting regulatory attitudes abruptly altered market dynamics.
By late 2025 and moving into early 2026, the market entered a sharp corrective phase. Unlike the rapid, panic-driven liquidations of 2022, the 2026 bear market was characterized by a grinding, sustained reduction in asset prices that culminated in a historic 50% wipeout of total market capitalization. Measured purely in dollar terms, the asset contraction required market participants to move significantly larger volumes of tokens simply to achieve the same economic throughput as previous years. Yet, rather than retreating from the ecosystem, users worldwide leaned more heavily into alternative on-chain mechanisms, preventing the catastrophic volume drops witnessed in past market downturns.
Comprehensive Data Analysis and Shifting Market Dynamics
A granular breakdown of on-chain data illustrates stark contrasts between speculative trading channels and utility-driven transactions. While traditional service inflows—comprising centralized exchanges, decentralized finance (DeFi) protocols, and lending platforms—experienced a slight 4.3% decline from $9.30 trillion to $8.90 trillion, other segments of the ecosystem achieved staggering growth.

Retail-level participation proved remarkably persistent throughout the bear market. Small-dollar inflows into crypto services saw exponential increases, with transfers under $100 surging by 78.4% and transactions ranging from $100 to $1,000 rising by 58.6%. Although these retail-sized transfers accounted for $273 billion of the nearly $10 trillion in aggregate activity, their upward trajectory underscores enduring grassroots engagement. Similarly, institutional-sized transfers of $1 million or more demonstrated high resilience, contracting by only 7.2% period-over-period. Given that institutional portfolios had depreciated by up to 50% due to falling asset prices, maintaining this level of transaction volume indicates that large-scale allocators maintained active liquidity strategies rather than abandoning the market entirely.
The most profound divergence, however, occurred within peer-to-peer and stablecoin transfer networks. While centralized trading volumes contracted alongside sentiment, domestic peer-to-peer transactions executed directly between personal wallets skyrocketed by 302.9%, climbing from $56.8 billion to $228.7 billion. P2P activity expanded its market share across all eight global regions tracked by the report. Analysts attribute this shift to the underlying composition of these channels: whereas exchange inflows remain highly sensitive to asset price fluctuations, peer-to-peer networks are now overwhelmingly dominated—approximately 96%—by stablecoins.
Explosive Growth in Cross-Border Stablecoin Corridors
Stablecoins emerged as the undisputed anchor of the global crypto economy during the 2026 downturn, fueled by emerging regulatory frameworks such as the GENIUS Act in the United States, Markets in Crypto-Assets (MiCA) regulation in the European Union, and progressive policy actions in Japan, Hong Kong, Singapore, and the United Kingdom.

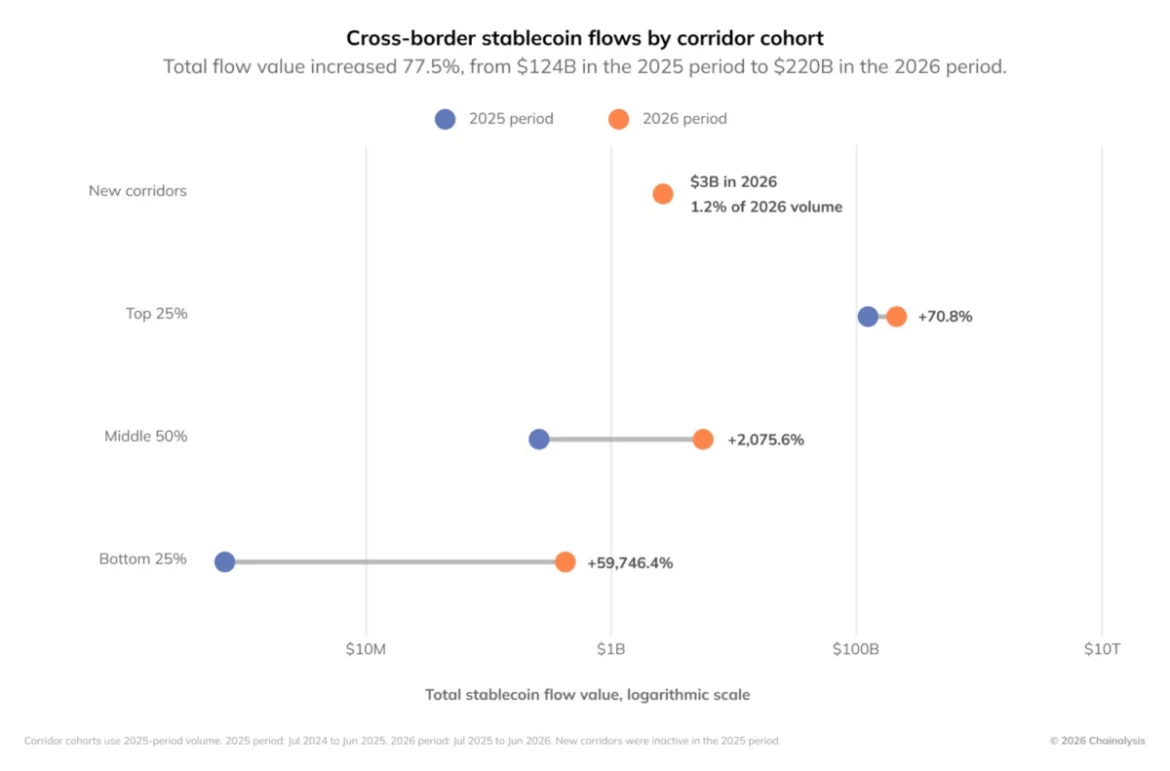
Conservative estimates indicate that monthly cross-border stablecoin value more than doubled, rising from $11 billion in January 2025 to $24 billion by June 2026. Total cross-border stablecoin flows surged 77.5% over the 12-month period, expanding from $124.2 billion to $220.3 billion. Crucially, the average size of these cross-border transactions hovered around $3,000—a threshold far too small for institutional capital, pointing instead to everyday commercial use cases such as merchant payments, family remittances, and capital flight from unstable domestic fiat currencies.
Industry leadership has taken note of this structural evolution. Philip Gradwell, vice president of economics at Tether, observed that on-chain movement has transitioned from erratic speculative bursts to steady, rhythmic routing through personal wallets. "Activity has become consistent, routed through wallets in a steady rhythm rather than in bursts," Gradwell stated, adding that "that is the signature of trade and business activity, not speculation."
The expansion of trade corridors further highlights this utility-driven adoption. The top quartile of global payment corridors accounted for 96.1% of cross-border stablecoin value, growing by 70.8%. More notably, activity expanded rapidly into secondary and tertiary trade routes. The bottom three quartiles of corridors, which previously recorded negligible volume totaling just $0.26 billion, carried $8.66 billion during the 2026 period. Researchers tracked 4,708 newly established corridors generating a cumulative $2.64 billion in volume, driven largely by the widespread utilization of USDT. "The real power of USDT is in the long tail, the parts of the economy that were priced out or shut out because traditional financial technology was too expensive or too restricted," Gradwell noted. "USDT can serve them because it costs on average one cent per transaction, settles instantly, and needs nothing more than a phone."

Regional Divergence and Grassroots Adoption Rankings
Geographically, the impact of the bear market was felt unevenly, with several emerging regions successfully bucking the global downturn. Latin America emerged as a standout performer, expanding its regional crypto economy by 9.8% period-over-period. This growth was propelled by a widespread regional pivot toward stablecoins and the utilization of digital assets as an effective hedge against persistent domestic currency volatility. Similarly, Sub-Saharan Africa led the world in specific growth metrics, driven by exceptionally strong peer-to-peer adoption and grassroots economic necessity.
When evaluating overall grassroots adoption through a rigorous methodology that weights service flows, domestic P2P transactions, on-chain asset balances, and cross-border transfers against purchasing power parity (PPP), Brazil secured the number one global ranking. Although Brazil did not claim the top spot in any single isolated sub-index, its consistent, high-level performance across all four categories allowed it to surpass more established markets like the United States, anchoring a domestic crypto economy valued at $252.5 billion.
The top twenty countries ranked by grassroots crypto adoption for the 2026 reporting period are as follows:

- Brazil
- United States of America
- Nigeria
- Japan
- Republic of Korea
- India
- Ukraine
- Thailand
- South Africa
- Canada
- Mexico
- China
- Germany
- Indonesia
- Australia
- Russian Federation
- United Kingdom of Great Britain and Northern Ireland
- Viet Nam
- Philippines
- Türkiye
Methodological Evolution and Industry Implications
To maintain analytical precision in tracking these trends, researchers introduced a revised methodology for the seventh annual Geographies report. The updated adoption index evaluates the geometric mean of four normalized sub-indices: service inflows, domestic P2P transactions, cross-border flows, and accumulated on-chain wallet balances. This mathematical approach ensures that countries demonstrating balanced, multi-dimensional adoption are accurately prioritized over nations dominated by single-category metrics. Furthermore, raw economic values are adjusted using the square root of each country’s GDP per capita, ensuring that local wealth influences geographic distribution proportionally without overshadowing true grassroots activity.
The broader implications of these findings suggest that the cryptocurrency industry has entered a new phase of economic maturation. While speculative cycles and asset price drawdowns will likely remain a hallmark of digital asset markets, the underlying infrastructure is increasingly supported by non-speculative, transactional demand. As stablecoin balances held firm between $98 billion and $109 billion throughout the nine-month market contraction—ultimately expanding their share of global on-chain balances to 22.5%—they functioned as a reliable financial anchor for millions of users worldwide.
Industry analysts conclude that the 2025–2026 bear market served as a profound stress test for blockchain technology. By demonstrating resilience in the face of a $2.1 trillion market contraction, the global crypto economy has signaled that its long-term viability is increasingly rooted in real-world utility, cross-border financial inclusion, and pragmatic economic survival.