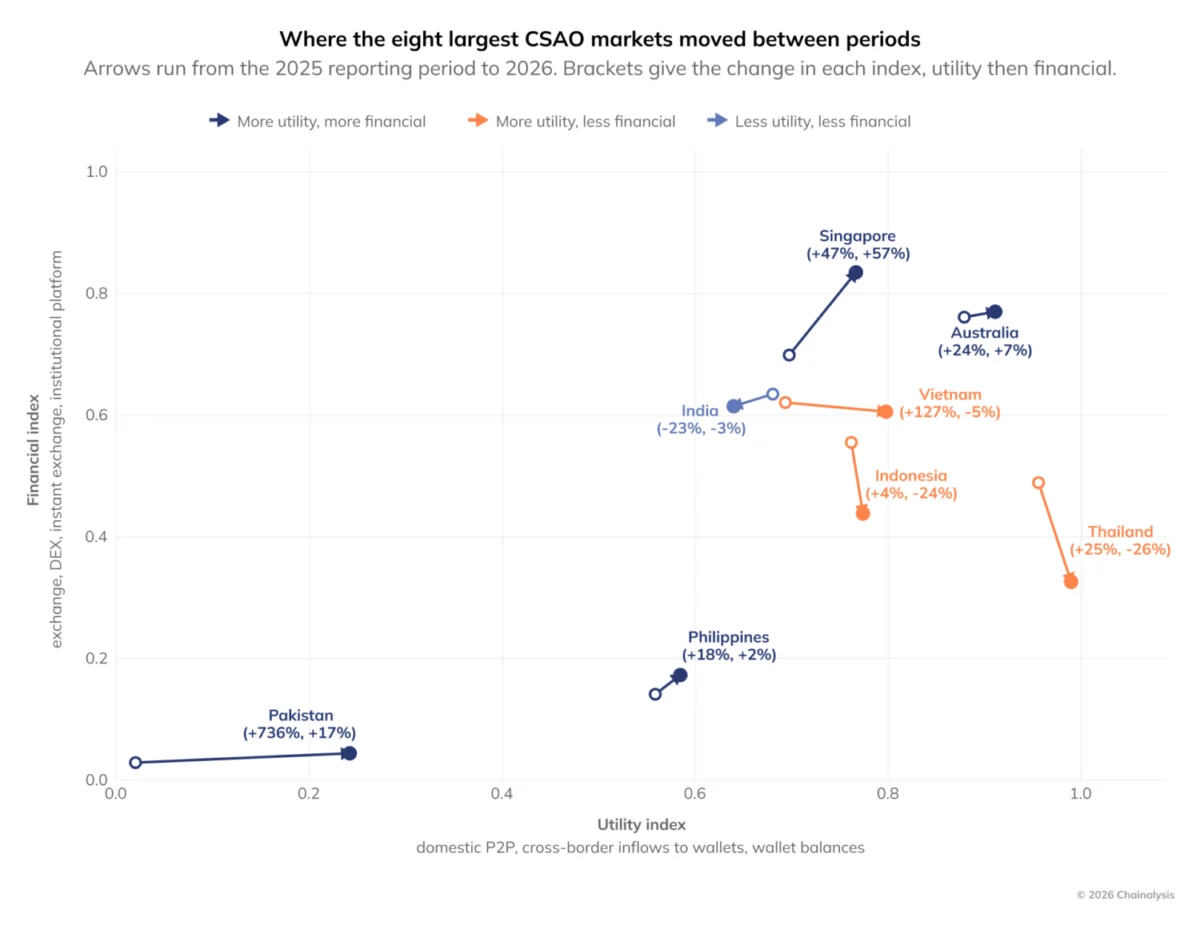
The digital asset landscape across Central and Southeast Asia and Oceania (CSAO) is undergoing a structural evolution, transitioning from speculative retail trading toward institutional integration and practical financial utility. According to regional market data covering the period from July 1, 2025, to June 30, 2026, the overall regional crypto economy experienced a slight contraction of 6.8%. Despite this macro-level cooling—largely influenced by broader global bear market trends—the region demonstrated remarkable resilience and internal diversity. Markets across CSAO recorded significant upticks in specialized use cases, including tokenization, cross-border business settlements, and peer-to-peer (P2P) transfers.

As regulatory frameworks mature and institutional players formalize their digital asset strategies, the definition of crypto adoption in CSAO is fundamentally changing. Financial institutions, corporate treasuries, and regional regulators are increasingly viewing blockchain technology less as a speculative asset class and more as foundational market infrastructure. This transformation is reshaping the region’s largest economies—Singapore, Australia, and India—while simultaneously unlocking new utility-driven growth in emerging markets such as Pakistan, the Philippines, Thailand, and Vietnam.
Regional Overview and Macro-Level Trends
Ranked as the sixth-largest crypto region globally, CSAO exhibits a complex mosaic of adoption drivers. While total transaction volumes dipped during the 2025–2026 monitoring window, localized growth persisted across distinct operational verticals. In financial hubs like Singapore and Australia, institutional participation expanded dramatically. Conversely, developing economies in Southeast Asia—specifically the Philippines, Thailand, and Vietnam—outperformed global benchmarks in peer-to-peer economic activity, driven by the practical demands of everyday financial life.

The dichotomy between financial indexing and utility indexing highlights this divergence. Financial activity, tracked through digital asset inflows into centralized and decentralized exchanges, remained dominant in high-income markets. Meanwhile, utility metrics—encompassing P2P payments, domestic remittances, and cross-border value transfers—surged in developing nations where traditional banking rails often involve higher friction and cost. Stablecoins emerged as the undisputed instrument of choice for moving value across international borders, vastly outpacing domestic stablecoin utilization in every market analyzed within the region.
Institutional Maturation in Singapore and Australia
The most pronounced shift within the CSAO region is the rapid institutionalization of digital asset markets, led primarily by Singapore and Australia. Together, these two financial powerhouses represent a massive share of the region’s total digital asset economy, though their internal compositions reflect distinct regulatory and market conditions.

Singapore cemented its status as the premier regional crypto hub, recording $284 billion in total crypto activity during the 2026 tracking period—a robust 55.4% year-over-year increase. A substantial catalyst for this growth was institutional-platform activity, which surged 94% to reach $60 billion. This capital was heavily concentrated among specialized market makers, over-the-counter (OTC) trading desks, and institutional brokerages. Furthermore, Singapore’s regulatory clarity, anchored by the Monetary Authority of Singapore’s (MAS) Digital Payment Token (DPT) licensing regime and its finalized stablecoin framework, provided the legal certainty required for traditional financial institutions to expand their digital asset offerings. Consequently, Singapore’s self-custody metrics dropped from historical highs to 28% by mid-2026, indicating a broad migration of capital into regulated custodial services and institutional platforms.
Australia followed closely as the region’s second-largest digital asset economy, generating $173.1 billion in activity. Although overall volume contracted by 5.6% due to a sharp decline in decentralized exchange (DEX) activity, institutional-platform inflows rose 33.3% to $39.92 billion. Market makers, prime brokers, and custodians absorbed nearly a quarter of all service inflows into the country. Industry experts attribute this institutional resilience to the introduction of regulated investment products, such as exchange-traded funds (ETFs) and retirement account allocations, alongside impending regulatory frameworks like the Australian Securities and Investments Commission’s (ASIC) digital asset licensing regime scheduled for 2027.

Utility-Driven Growth and Stablecoin Dominance
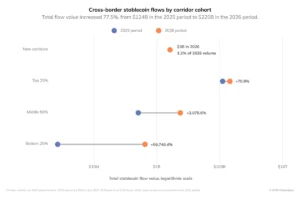
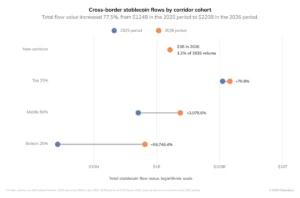
While institutional platforms captured billions in high-end financial markets, everyday utility drove adoption across Southeast Asia and South Asia. Stablecoins, in particular, established themselves as the premier vehicle for international trade and cross-border remittances. Across the CSAO region, cross-border stablecoin activity exceeded domestic usage by an average ratio of 3.2 to 1, with Malaysia exhibiting the widest disparity at 29.5 times.
This phenomenon is largely attributed to the efficiency of domestic digital payment rails in countries like Malaysia, which reduce the necessity of stablecoins for internal retail transactions. However, for cross-border settlements, corporate treasuries and regional merchants increasingly bypass traditional banking delays and high wire fees by deploying regulated stablecoins. In the Philippines—the fourth-largest remittance market globally—industry leaders estimate that between 5% and 10% of inbound remittances are now settled using stablecoins, prompting major international remittance providers to integrate blockchain rails into their legacy operations.

Simultaneously, small-value peer-to-peer (P2P) transfers flourished in the Philippines, Thailand, and Vietnam. Despite representing only 2.5% of the global crypto economy by valuation, these three nations accounted for 14.4% of the world’s small-value P2P transfers (under $10,000) during the 2026 period, totaling 5.4 million transactions. More than 80% of domestic transfers in these countries fell below $1,000, underscoring grassroots utility for unbanked and underbanked populations.
Regulatory Evolution and Market Shifts in South Asia
South Asia presented a contrasting narrative marked by regulatory reform and market readjustment. India experienced a 14.7% contraction in its overall crypto economy amid the global bear market, yet it maintained massive absolute scale with $135 billion in economic activity. Notably, India remained the CSAO region’s largest market for centralized exchange (CEX) inflows, pulling in $88.4 billion.

Market observers in India noted a distinct maturation in retail and institutional investor psychology, shifting away from short-term speculative flipping toward long-term accumulation and asset diversification alongside traditional equities and gold. However, local exchange volumes continued to face headwinds due to domestic tax frictions, specifically a 1% tax deducted at source (TDS) on virtual digital asset transactions introduced in 2022. This policy has driven a significant portion of domestic trading volume toward offshore platforms.
Meanwhile, Pakistan recorded a dramatic 736% surge in utility activity, jumping from $69 million to $351 million. While this growth occurred off a very shallow baseline, it coincided with a monumental regulatory milestone: the formal relaxation of a seven-year ban that had previously prohibited Pakistani commercial banks from servicing cryptocurrency companies, signaling a tentative opening for the country’s nascent digital asset sector.

Broader Economic Implications and Future Outlook
The trajectory of the Central and Southeast Asia and Oceania crypto economy heading into the latter half of the decade points toward deeper systemic integration. Financial institutions across the region are no longer debating whether to engage with digital assets, but rather how to operationalize blockchain infrastructure safely and compliantly. Initiatives such as Project Acacia—a collaborative venture between the Reserve Bank of Australia and the Digital Finance Cooperative Research Centre exploring tokenized wholesale assets—exemplify this institutional pivot toward real-world asset (RWA) tokenization and liquidity management.
Industry leaders emphasize that this heightened institutional involvement raises the stakes for the entire sector. Maintaining rigorous regulatory compliance, robust cybersecurity protocols, and transparent asset management will be vital to preserving the fragile trust established between the crypto industry, mainstream financial institutions, and national regulators. As market participants across Singapore, Australia, India, and Southeast Asia continue to build out compliant infrastructure, the region is successfully bridging the gap between speculative digital trading and durable financial utility.