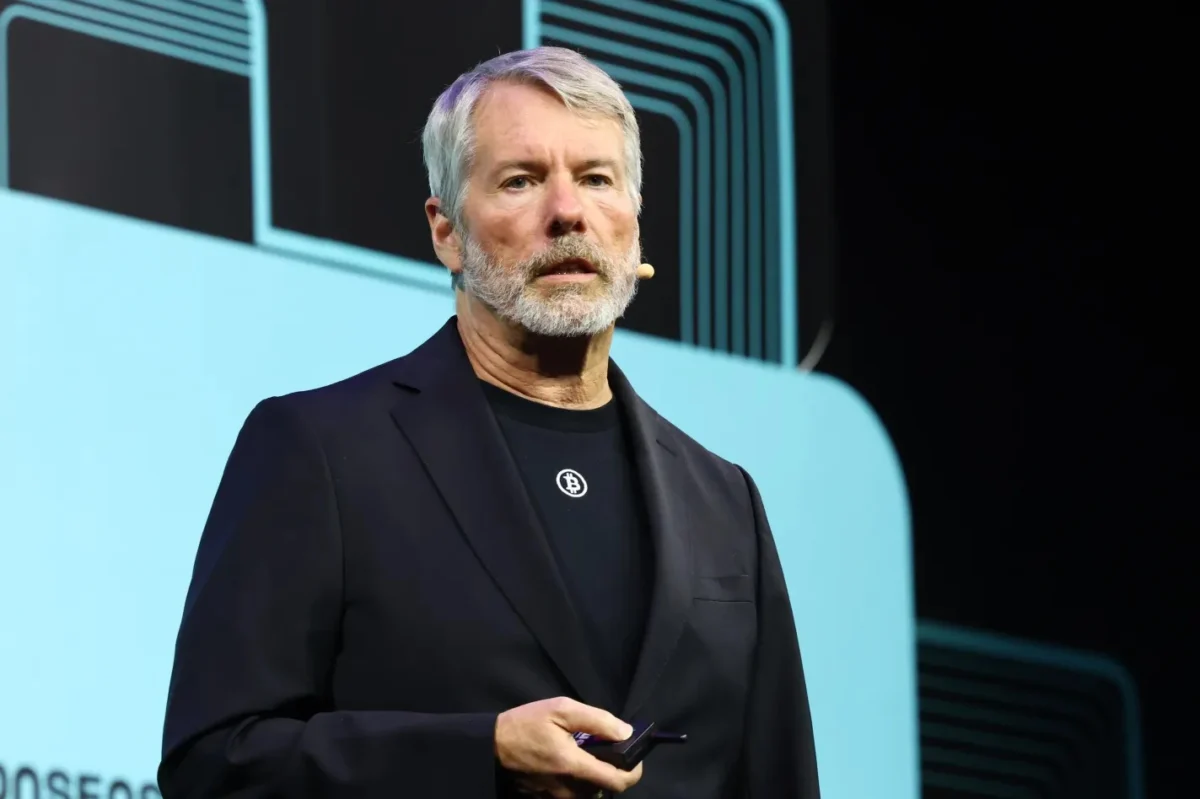
The financial strategy of corporate Bitcoin accumulation has once again sparked intense debate within the digital asset community, placing executive chairman Michael Saylor and his corporate treasury vehicle, Strategy, at the center of a public dispute. The controversy erupted following a series of regulatory filings detailing fresh share sales, insider stock liquidations, and a nuanced disagreement over how corporate value is measured during aggressive expansion cycles. At the heart of the friction is a growing tension between traditional corporate finance metrics and the unique, hyper-focused Bitcoin accumulation models pioneered by Strategy, a company that now holds a monumental fraction of the global circulating supply of the world’s leading cryptocurrency.
The debate underscores the complex mechanics of corporate capitalization in the digital asset era. As Strategy pushes its cash reserves toward the $1-billion threshold, market observers, analysts, and shareholders are increasingly scrutinizing the balance between asset accumulation, share dilution, and liquidity management. This comprehensive review examines the origins of the recent dispute, the defense mounted by leadership, the underlying financial metrics, and the broader implications for institutional Bitcoin strategies.
The Genesis of the Dispute: Capital Raises and Share Dilution
The current public sparring trace its roots to regulatory documents submitted to the United States Securities and Exchange Commission (SEC). On June 8, Strategy filed an 8-K disclosure detailing the sale of more than 1.4 million shares of its Class A common stock (MSTR), generating approximately $181 million in gross proceeds. While equity offerings have become a routine mechanism for the firm to fund its ongoing cryptocurrency purchases, the timing and execution of this particular round coincided with other notable corporate movements.
During the same week, top Strategy executives sold roughly $15 million worth of their personal stock holdings. Company representatives subsequently clarified that these insider sales were executed primarily to cover statutory tax obligations associated with equity-based compensation vesting schedules. Nevertheless, the simultaneous occurrence of corporate share dilution and insider liquidations compounded existing anxieties among investors who closely monitor the firm’s equity health.
Compounding the unease, market reports revealed that Strategy had briefly parted with 32 Bitcoin the previous week—a nominal amount relative to its total holdings, but a rare deviation from its strict accumulation ethos. However, the company swiftly pivoted back to its aggressive buying posture just days later, announcing a fresh $101 million acquisition of Bitcoin at an average price of $65,332 per coin.
Matthew Kratter Opens the Debate on BTC Yield
The convergence of these events prompted a sharp reaction from prominent cryptocurrency analyst Matthew Kratter. Taking to social media platform X, Kratter fired the opening salvo in what would quickly become a widely discussed industry debate. He argued that data provided by Strategy itself demonstrated that existing shareholders were financially worse off following the latest round of capital raising.
Kratter’s argument hinged on a proprietary performance indicator developed by the company known as "BTC Yield." This metric is designed to track the percentage change in the ratio of Bitcoin held by the firm relative to its fully diluted shares outstanding over a given period. Analyzing an updated corporate chart showing total Bitcoin holdings at 843,706 against a diluted share count of 384,180, Kratter contended that the rate of share dilution had outpaced the growth rate of the underlying Bitcoin inventory during the transaction window, effectively reducing the per-share Bitcoin claim for existing investors.
Michael Saylor’s Direct Rebuttal and the Defense of Total Accretion
Michael Saylor dismissed Kratter’s interpretation, utilizing X to offer a detailed structural defense of the transaction and the true mechanics of the BTC Yield metric.
Saylor clarified that BTC Yield is intentionally narrow in its scope, measuring exclusively the physical quantity of Bitcoin held per share. By design, it does not account for simultaneous additions of fiat currency, cash equivalents, or other non-Bitcoin assets to the corporate balance sheet.
According to Saylor, the capital-raising transaction in question was not merely a mechanism to acquire Bitcoin, but a dual-asset acquisition. The offering successfully added both 1,550 Bitcoin and $100 million in United States Dollar reserves to Strategy’s treasury balance. When both the digital asset appreciation and the substantial fiat cash injection are factored into the overall valuation equation, Saylor maintained that the transaction was fundamentally accretive—rather than dilutive—to MSTR shareholders.
In his published statement, Saylor emphasized: "BTC Yield measures the increase in BTC per share, not total shareholder accretion. Last week Strategy added 1,550 of BTC and $100 million of USD Reserve. When both assets are included, the transaction was accretive to MSTR shareholders."
The Billion-Dollar Buffer: Cash Reserves and Dividend Obligations
The influx of capital from the recent share sales has propelled Strategy’s liquid dollar reserves to just under $1 billion, establishing a robust financial buffer that plays a critical role in the company’s broader operational framework.
As of the latest disclosures, Strategy’s cumulative Bitcoin treasury stands at an astounding 845,256 BTC, valued at approximately $52 billion based on prevailing market prices. Performance metrics for the year to date highlight the sheer scale of the operation, with the company’s BTC Yield resting at 12.8% and total year-to-date BTC gains reaching 86,328 coins.

Beyond serving as dry powder for opportunistic cryptocurrency market dips, this expanding cash reserve fulfills an essential corporate governance function. On June 8, Strategy shareholders formally approved the implementation of semi-monthly cash dividends on the company’s STRC preferred stock series. Sustaining reliable, recurring dividend distributions of this magnitude requires a dependable and highly liquid pool of capital. By maintaining a nearly $1-billion cash cushion alongside its volatile digital asset holdings, Strategy aims to mitigate liquidity risks and ensure uninterrupted payouts to preferred equity holders, even during prolonged periods of broader cryptocurrency market consolidation or downturns.
Chronology of Events Leading to the Controversy
To fully understand the context of the recent debate, it is helpful to review the chronological sequence of corporate actions and market reactions:
- Late May 2026: Strategy continues its methodical tracking of digital assets, occasionally reviewing treasury allocations and monitoring overall macro market conditions as Bitcoin trades within a consolidation range.
- Early June 2026: Reports circulate regarding the divestment of 32 Bitcoin by Strategy, causing brief speculative chatter among digital asset analytics communities.
- June 8, 2026 (Morning): Strategy submits an official 8-K regulatory filing to the SEC, detailing the sale of over 1.4 million MSTR shares resulting in approximately $181 million in gross capital proceeds. Concurrently, disclosures reveal insider stock sales totaling roughly $15 million, attributed to executive tax obligations.
- June 8, 2026 (Later): Strategy shareholders formally approve semi-monthly dividend disbursements for the company’s STRC preferred stock series.
- June 8–9, 2026: Analyst Matthew Kratter publishes an analytical critique on X, arguing that the recent share issuance resulted in negative per-share accretion based on the BTC Yield metric.
- June 9, 2026: Michael Saylor responds publicly via X, defending the equity offering by pointing out that the transaction added both 1,550 Bitcoin and $100 million in USD reserves, making the move accretive when evaluated across all treasury assets.
- June 10, 2026: Strategy executes a follow-up announcement detailing a new $101 million Bitcoin acquisition, purchasing additional coins at an average price of $65,332 per unit, thereby lifting its total holdings to 845,256 BTC and pushing cash reserves toward the $1-billion milestone.
Broader Implications for Corporate Treasury Strategies
The public debate between Kratter and Saylor illuminates a fundamental evolutionary step in how public companies manage balance sheets in the digital age. Traditional corporate finance models evaluate shareholder dilution primarily through earnings per share (EPS), return on equity (ROE), and cash flow generation. However, firms like Strategy operate effectively as hybrid operating companies and closed-end digital asset funds, creating unique analytical challenges for Wall Street analysts and retail investors alike.
When a company routinely issues equity to acquire a non-yielding, highly volatile asset like Bitcoin, standard valuation models often break down. Critics argue that persistent share dilution can erode long-term value if the growth of the underlying asset fails to outpace the expansion of the share supply. Conversely, proponents argue that utilizing a high equity valuation to acquire scarce digital assets creates a compounding feedback loop, permanently increasing the per-share claim on an asset with a strictly capped lifetime supply of 21 million units.
The introduction of substantial cash reserves—approaching $1 billion in Strategy’s case—adds yet another layer of complexity. By holding significant fiat liquidity alongside its massive Bitcoin stash, the company is attempting to bridge the gap between traditional corporate finance obligations (such as preferred stock dividends and debt servicing) and an aggressive, conviction-driven cryptocurrency accumulation strategy.
As Strategy continues to scale its operations, the scrutiny surrounding its financial engineering will likely intensify. Market participants will continue to debate whether metrics like BTC Yield capture the full picture of corporate health or whether traditional balance sheet metrics must be completely reimagined for firms operating on a Bitcoin standard. For now, Michael Saylor and his executive team remain steadfast in their approach, utilizing every tool at their disposal—from equity markets and fiat cash buffers to continuous digital asset acquisitions—to reinforce their position as the preeminent corporate holder of Bitcoin in the global financial system.