The landscape of global hardware markets and cryptocurrency mining has undergone a seismic shift, driven primarily by sweeping regulatory actions in China. As Beijing intensifies its nationwide crackdown on cryptocurrency mining and trading operations, industrial-scale miners are hastily liquidating their assets. Thousands of high-performance graphics processing units (GPUs), including advanced Nvidia and AMD architectures, are flooding the second-hand market at heavily discounted prices. While the influx of cheap hardware might initially seem like a windfall for gamers and PC enthusiasts desperate for relief from years of acute shortages and inflated prices, a closer examination of the market reveals complex underlying challenges. Miners are encountering significant hurdles in offloading their inventory, and broader macroeconomic factors continue to dictate the rhythm of both the semiconductor industry and the broader digital asset economy.
Regulatory Origins and the Great Miner Migration
The genesis of this hardware surplus lies in the aggressive policy maneuvers executed by Chinese authorities. For years, China served as the undisputed epicenter for global Bitcoin mining, housing a vast majority of the world’s hash rate due to cheap electricity and an abundance of specialized hardware manufacturing infrastructure. However, mounting concerns over environmental sustainability, financial stability, and energy consumption prompted the State Council and provincial governments to issue sweeping bans on cryptocurrency mining activities.
Provinces such as Sichuan, Xinjiang, Inner Mongolia, and Qinghai—once bustling hubs characterized by sprawling warehouse-style facilities packed with application-specific integrated circuits (ASICs) and GPU rigs—were systematically targeted. Authorities ordered local power grids to cut off electricity supplies to mining farms, and law enforcement agencies launched coordinated raids.
Faced with this hostile domestic regulatory environment, miners were forced to make a stark choice: relocate their operations or liquidate. While a fraction of large-scale industrial miners successfully migrated their equipment to crypto-friendly jurisdictions in North America, Central Asia, and Scandinavia, countless smaller or mid-tier operators found relocation logistically impossible or cost-prohibitive. Consequently, these operators opted for complete liquidation, stripping down their mining rigs and flooding the open market with used graphics cards.
Chronology of the Hardware Liquidation Wave
The liquidation process began in earnest following the initial wave of provincial bans in mid-2021. As enforcement tightened across the spring and summer months, the secondary market experienced a sudden surge in supply.
Phase one involved localized sell-offs on domestic Chinese e-commerce and classified platforms such as Xianyu, a subsidiary of Alibaba. Initially, prices remained relatively stable as miners sought to recoup their capital investments. However, as the realization set in that the crackdown was permanent and irreversible, panic selling ensued.
By mid-2021, the volume of available hardware outpaced local demand. Sellers began slashing prices week over week to attract buyers. Models spanning multiple generations—ranging from older architectures like Nvidia’s Pascal and AMD’s Polaris to cutting-edge Ampere (RTX 30-series) and RDNA2 chips—appeared in unprecedented quantities.
Simultaneously, ancillary equipment such as specialized mining motherboards, power supply units (PSUs), and even pre-configured mining laptops began to populate the secondary listings. This glut of hardware quickly spilled beyond domestic borders, influencing international shipping channels and signaling the potential end of the global GPU shortage that had plagued consumers since the onset of the COVID-19 pandemic.
Market Data and Pricing Realities
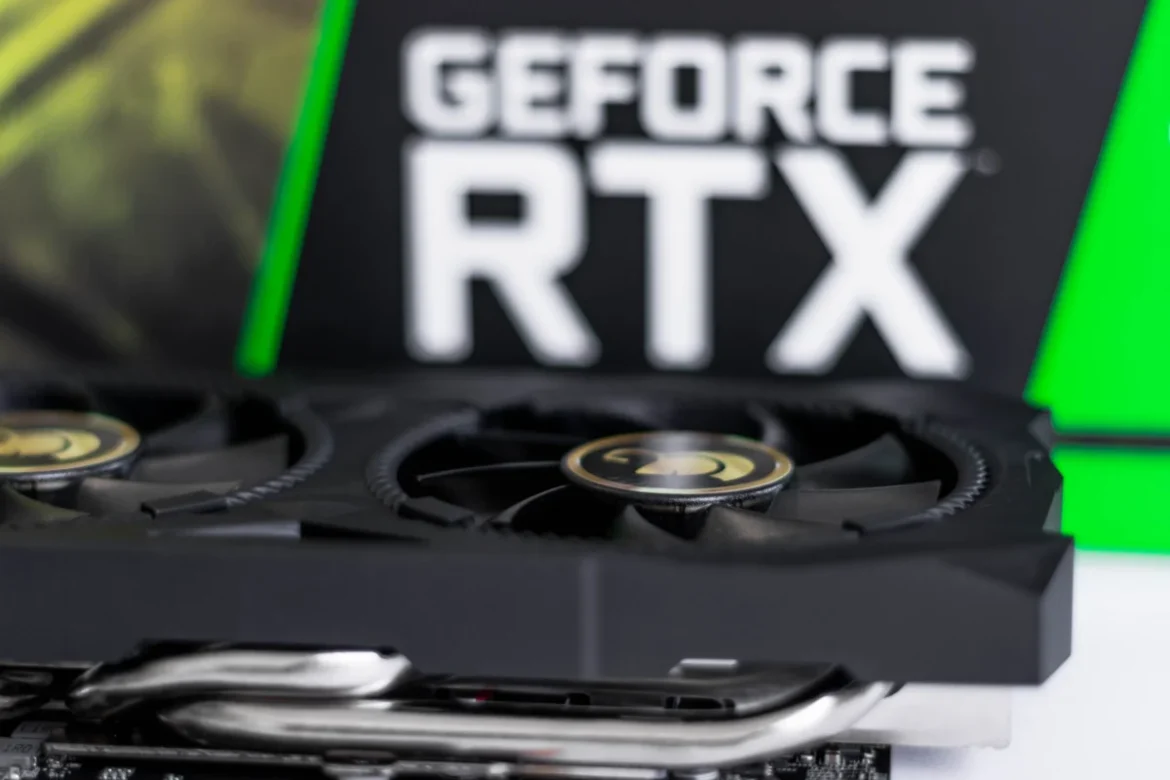
The oversupply of hardware has driven secondary market prices down to levels not seen in years, though these figures come with specific caveats. On various online Chinese marketplaces, the popular Nvidia GeForce RTX 3060 GPU has been spotted trading for as low as $270 per unit. Higher-tier cards have seen similar drastic markdowns: the RTX 3060 Ti has commanded prices around $350, while the more powerful RTX 3070 has changed hands for approximately $400. Furthermore, specialized mining setups, including laptops outfitted with RTX 3060 cards operated continuously for mining purposes, have been listed in bulk for roughly $1,000 per unit.
Despite these enticing price points, the transaction volume remains sluggish. Industry analysts and market observers point to several primary deterrents for prospective buyers. First, the vast majority of these discounted GPUs are not sold individually. To manage logistics and clear inventory rapidly, sellers typically mandate minimum purchase orders ranging from 100 to 200 units per transaction. This wholesale requirement effectively locks out individual retail consumers, gamers, and small system builders, restricting buyers to well-capitalized liquidators, regional brokers, or large-scale refurbishers.
Second, severe concerns regarding hardware longevity plague the inventory. Graphics cards deployed in commercial mining operations are typically subjected to grueling conditions, running continuously at maximum capacity twenty-four hours a day, seven days a week. To maximize mining yields, operators frequently overclock the memory and core clocks while running cooling fans at maximum RPMs. This sustained thermal and electrical stress accelerates the degradation of vital components, particularly the VRAM modules, voltage regulator modules (VRMs), and cooling fans, significantly shortening the expected lifespan of the hardware.
Industry Reactions and Manufacturer Perspectives

The sudden influx of ex-mining hardware has prompted responses from key industry stakeholders, including major hardware manufacturers and blockchain developers. Executives at Nvidia and AMD have closely monitored the secondary market shifts, recognizing that the liquidation wave fundamentally alters the supply-demand dynamics for new retail products.
During industry conferences and earnings calls held around mid-2021, tech executives acknowledged the shifting tides. Nvidia’s leadership noted that while the primary market had been constrained by an acute shortage of semiconductor manufacturing capacity and unprecedented consumer demand, the secondary market saturation indicated a normalization of channel inventories.
Furthermore, the broader technological landscape has begun shifting away from GPU-reliant consensus mechanisms. Ethereum, historically the dominant blockchain network mined using consumer graphics cards, initiated a multi-year transition toward a Proof-of-Stake (PoS) consensus mechanism, culminating in "The Merge." This technological evolution signaled to miners that the long-term viability of GPU-based mining was diminishing rapidly, accelerating the decision to dump hardware before future upgrades rendered their equipment entirely obsolete for mining purposes.
Geopolitical and Macroeconomic Implications
The forced exodus of mining capital from China has far-reaching macroeconomic and geopolitical consequences. As Beijing systematically excised cryptocurrency operations from its borders, global hash rate distributions shifted dramatically. Western mining firms, particularly those based in the United States, Canada, and parts of Europe, capitalized on the regulatory vacuum, securing substantial market share and institutional investment.
Domestically, China’s aggressive stance against decentralized cryptocurrencies was immediately paired with a state-backed alternative: the accelerated development and testing of the digital Yuan (e-CNY). By systematically removing decentralized assets from its financial ecosystem, the People’s Bank of China sought to consolidate monetary control, utilizing the digital sovereign currency to monitor transactions and enhance domestic economic oversight.
For the global consumer electronics market, the liquidation wave served as an early indicator of easing supply constraints. Alongside China’s mining crackdown, international logistics began to recover, and regional markets—such as Germany and other European territories—reported significant drops in retail GPU premiums, with some channel markups falling by up to 40% compared to peak shortage periods.
Broader Cryptocurrency Market Context

While hardware markets absorbed the shock of the miner sell-off, the broader digital asset economy navigated a period of intense consolidation. During the height of the hardware liquidation phase, flagship cryptocurrencies like Bitcoin (BTC) traded within a tightly bounded range, hovering near the $33,000 threshold. Despite posting marginal intraday gains, BTC struggled to breach stubborn technical resistance levels near $35,000, reflecting broader market uncertainty.
The convergence of regulatory pressure from the world’s second-largest economy, shifting consensus mechanisms within major blockchain networks, and the sudden decentralization of global hash rates created a uniquely complex environment for digital asset investors. Analysts noted that while short-term price action remained range-bound, the structural maturation of the mining industry—transitioning from informal, fragmented Chinese outfits to institutionalized, publicly traded Western corporations—marked a permanent turning point for the sector.
Conclusion and Future Outlook
The mass liquidation of Nvidia and AMD graphics cards by Chinese crypto miners stands as a watershed moment at the intersection of regulatory policy, technological evolution, and global supply chains. What began as a government-enforced crackdown on industrial energy consumption resulted in a massive secondary market correction, offering a glimpse into the fragility of hardware ecosystems tied to speculative asset classes.
As the dust settles, the long-term implications remain clear: the era of unchecked, highly centralized GPU mining within China has drawn to a definitive close. Although secondary market hurdles such as bulk purchasing requirements and hardware wear-and-tear continue to frustrate retail consumers, the overall market is steadily regaining equilibrium. Moving forward, the lessons learned from the 2021 hardware glut will undoubtedly influence how both the semiconductor industry and regulatory bodies approach the delicate balance between technological innovation, energy consumption, and global economic stability.